They needed a better business plan
There are few British traditions quite as peculiar as celebrating the failure of a man who tried to blow up Parliament by setting fire to a dummy of him. Every November, we gather around bonfires, watch fireworks, eat something unhealthy and chant: “Remember, remember, the fifth of November.”
It is a curious national ritual. Most countries celebrate their heroes. The British, apparently, prefer to celebrate a man who failed spectacularly at his chosen profession.
This year, the British Chamber of Commerce in the Czech Republic brings that distinctly British tradition to its Guy Fawkes Gala Night on 6 November. And, as a Patron of the BCC, Aisa International is delighted to join the celebrations.
But behind the fireworks, there is a story about ambition, risk, poor planning and a rather unfortunate approach to long-term security. Which, as it happens, brings us rather neatly to financial planning (in case you were wondering where this was all going!).
Guy Fawkes, the original explosive entrepreneur
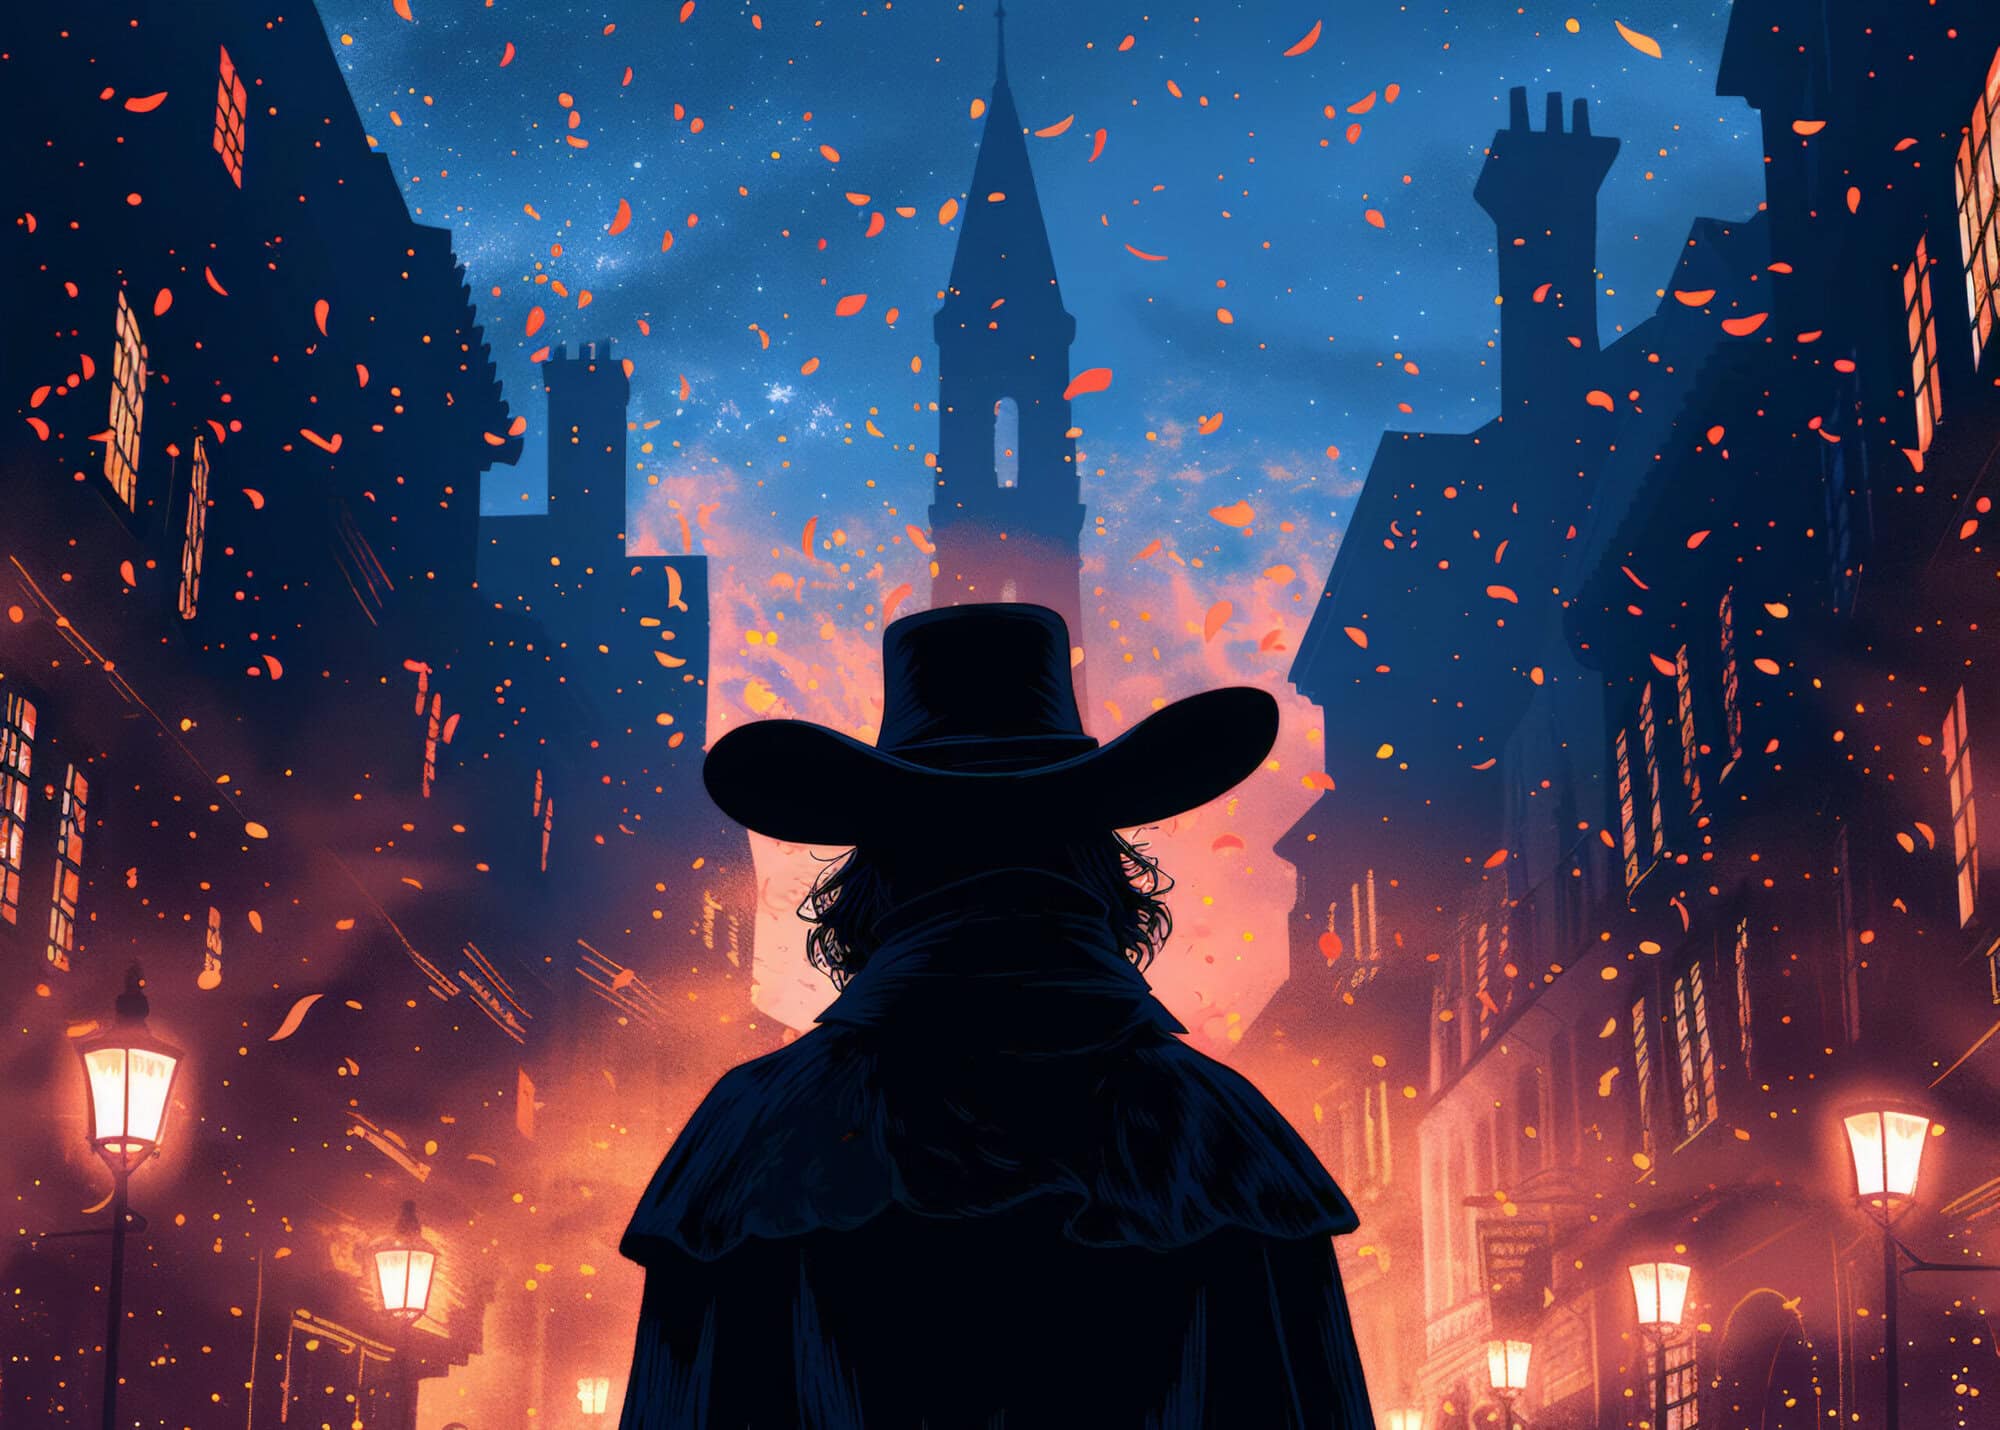
The year was 1605. King James I was on the throne, religious tensions were running high, and a group of English Catholics had decided that the best way to solve their political problems was to blow up the King and Parliament. Their plan was ambitious. They would hide barrels of gunpowder beneath the House of Lords and detonate them during the State Opening of Parliament.
It was, in modern business terminology, a high-risk strategy with potentially catastrophic consequences and absolutely no exit plan.
The principal organiser was Robert Catesby. Guy Fawkes was the military man entrusted with the explosives. He knew his way around gunpowder, having served as a soldier abroad, and was apparently the ideal candidate for a job involving 36 barrels of the stuff.
Unfortunately for Guy, someone sent an anonymous letter warning that something was amiss. On the night of 4 November, authorities searched the cellars beneath Parliament and found Fawkes guarding the explosives. His cover story? His name was John Johnson.
It was not the most convincing rebranding exercise in British history.
Imagine the LinkedIn profile-
John Johnson | Explosives Consultant | Special Projects, Westminster
Skills: Risk management. Strategic planning. Handling difficult stakeholders.
References available on request — subject to the survival of the referee.
Fawkes was arrested, interrogated and eventually confessed. The plot collapsed, his co-conspirators were pursued, and the surviving conspirators were convicted of treason.
So much for the business plan.
Guy Fawkes was not burned at the stake
Here is a little historical correction for anyone who thinks Guy Fawkes ended his days tied to a stake and surrounded by flames- which seems to be the popular misconception. He didn’t and the traditional punishment for high treason was to be hanged, drawn and quartered — a particularly gruesome execution that involved hanging, disembowelment and dismemberment.
Fawkes was sentenced to this punishment in January 1606. However, he reportedly jumped from the scaffold and broke his neck before the full sentence could be carried out. So, while his co-conspirators suffered the complete horror of the punishment, Fawkes avoided at least some of it.
In other words, Guy Fawkes was not burned alive. The burning effigies came later, as part of the annual commemorations of the plot’s failure.
The British have been getting the details wrong for centuries — which is reassuring for anyone who has ever misunderstood the small print on a financial product.
The last man to enter Parliament with honest intentions
It is tempting to describe Guy Fawkes as the last man to enter Parliament with honest intentions. Strictly speaking, his intentions were perfectly clear. It was the rest of the country that objected to them.
Still, there is something wonderfully British about a tradition that remembers a failed attempt to change the political establishment by blowing it up. These days, of course, we prefer our political upheaval to be conducted through elections, parliamentary debates and the occasional strongly worded newspaper column.
And if you want to make a difference to your own future, there are less explosive methods available.
You could start by reviewing your pension. It may not bring down the government, but it could make a considerable difference to your retirement.
A cautionary tale about risk
The most striking thing about the Gunpowder Plot is not the quantity of gunpowder involved. It is the extraordinary confidence the conspirators placed in a plan with so many ways to go wrong.
They had a target. They had a strategy. They had resources. What they lacked was a realistic assessment of the risks, a contingency plan and any sensible provision for what might happen if everything went wrong.
Sound familiar?
Of course, financial planning is a rather less dramatic business. But the underlying principle is remarkably similar. Understand the risks before committing yourself, prepare for the unexpected and don’t assume that everything will go according to plan.
At Aisa International, we help clients think about their financial futures through pension planning, investment planning and life insurance.
For British expatriates living in the Czech Republic, this can be particularly important. Living internationally may mean dealing with pensions accumulated in one country, investments held in another and family commitments that span several borders.
It can become complicated surprisingly quickly. The important thing is not to wait until the fuse is burning.
Plan for the long term
Guy Fawkes was thinking about one very big day. Your pension should be thinking about the many years that follow your working life.
Whether you have a UK pension, are building wealth while living in the Czech Republic, or need to understand how your retirement arrangements fit together across borders, it pays to review your position before retirement is upon you.
After all, retirement is one of the few major life events for which you can plan for decades — and still be surprised by how quickly it arrives.
Investments: don’t put all your gunpowder in one barrel
The Gunpowder Plot depended on concentrating an extraordinary amount of destructive potential in one place. In investment terms, concentration can also create risk — although a poorly performing portfolio is unlikely to bring down the House of Lords.
Diversification, an appropriate investment strategy and an understanding of your attitude to risk can all form part of sensible investment planning.
The right approach depends on your circumstances, objectives and time horizon. There is no magic formula, and anyone promising a risk-free route to riches should probably be treated with more suspicion than a man carrying barrels into Parliament after dark.
Life insurance: as life does not always go to plan
Guy Fawkes probably wasn’t thinking about financial protection for his family when he accepted his assignment. Given how things turned out, perhaps he should have been.
If your family relies on your income, it is worth considering what would happen financially if you were no longer there to provide it. Life insurance can help protect the people who matter to you against the financial consequences of an unexpected death, subject to the policy terms and conditions.
It is not the most exciting topic for a British Chamber of Commerce gala. Then again, neither is discovering that the family home, mortgage and children’s education all depend on one income.
Some things are better dealt with before there is a crisis.
Summary
Guy Fawkes had a plan, a deadline and a very memorable outcome. What he didn’t have was a Plan B.
Fortunately, you don’t need barrels of gunpowder, a disguise or a fictitious name to take control of your financial future. You just need to understand where you are now, where you want to be, and what steps may help you get there.
As we celebrate the spirit of Guy Fawkes Night at this year’s British Chamber of Commerce Gala, we can raise a glass to British history, enjoy the fireworks (if there are any) and be grateful that modern financial planning is considerably less explosive.
And remember, if your pension is a ticking time bomb, the best time to defuse it is before retirement.
