
Significantly reduce the tax you pay on your UK pension income in the Czech Republic
If you’re a British citizen planning retirement in the Czech Republic — perhaps with a Czech spouse or partner — there’s a valuable but often-overlooked piece of Czech tax law that could significantly reduce the tax you pay on your UK pension income. But it only works if your pension is structured the right way before you start drawing it.
The Opportunity: §4(1)(h) of the Czech Income Tax Act
Czech tax law contains a specific exemption for “regularly paid pensions.” Under Act No. 586/1992 Coll., §4(1)(h), pension income that is paid at set, recurring intervals is exempt from Czech income tax up to an annual cap (linked to the Czech minimum wage and adjusted periodically).
For a British retiree relocating to the Czech Republic — especially as part of a couple, where the exemption may apply per person — this can mean a meaningful chunk of retirement income arriving with no Czech tax liability at all, on top of favourable UK treatment.
The catch? It hinges entirely on one word: “regularly.”
The difference between an annuity-style, fixed drawdown schedule and an ad hoc lump sum could be the difference between a pension paid largely tax-free and one taxed as ordinary income in the Czech Republic.
Why This Is Trickier Than It Sounds for UK DC Pensions
If you hold a UK Defined Contribution (DC) pension — a SIPP or personal pension — you have enormous flexibility in how you draw it. That flexibility is usually a selling point. In this context, it can work against you.
Czech tax authorities interpret “regularly paid” fairly strictly. Broadly speaking:
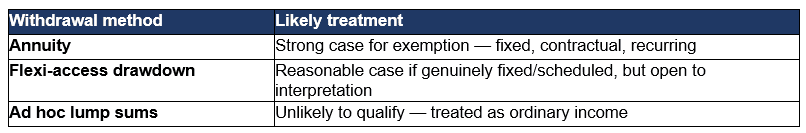
In other words, the same pension pot could be taxed very differently in the Czech Republic depending on how — not just how much — you withdraw from it.
It's Not Just a Czech Question — the UK Side Matters Too
Before Czech tax rules even come into play, you need to establish where your pension is taxable in the first place. This is where the UK-Czech Double Taxation Treaty comes in.
As a Czech tax resident, you can typically apply to HMRC for an NT (No Tax) code, so your pension provider pays your income gross rather than deducting UK tax at source. Under most double tax treaties, private and occupational pension income is taxable only in your country of residence — though government and civil service pensions are frequently carved out and remain UK-taxable regardless of where you live. The exact wording of the UK-Czech treaty needs checking against your specific pension type.
Get this step right, and your UK pension income becomes taxable in the Czech Republic — which is exactly where §4(1)(h) then becomes relevant.
What This Means for a UK-Czech Couple
If you’re a British citizen with a Czech spouse, both retiring together, there are a few extra angles worth considering:
- The exemption cap likely applies per person, not per household — so both partners’ pensions structured as regular drawdown may each benefit independently.
- Timing matters. Large lump-sum withdrawals taken before you become Czech tax resident are simply UK income taxed under UK rules at that time — sidestepping the “regular payment” question altogether. Once you’re Czech tax resident, the same withdrawal is judged by Czech criteria.
- Sequencing decisions are largely irreversible. Once pension income starts flowing under one structure, restructuring later can be difficult or costly. This is a “get it right before you move” situation, not a “fix it later” one.
The Bottom Line
A UK DC pension gives you the flexibility to draw it almost any way you like — but that flexibility is precisely what puts the Czech tax exemption at risk if you don’t plan the structure in advance. The difference between an annuity-style, fixed drawdown schedule and an ad hoc lump sum could be the difference between a pension paid largely tax-free and one taxed as ordinary income in the Czech Republic.
If you’re a few years out from retiring to the Czech Republic, now — not the year you move — is the time to look at:
- How your UK pension is currently structured, and whether it can be converted to a “regular” payment pattern
- Applying for relief at source under the UK-Czech treaty
- Sequencing any lump-sum withdrawals around your residency change
- Confirming the current annual cap under §4(1)(h), which moves with the Czech minimum wage
Every case depends on the specific pension type, timing of relocation, and personal circumstances of both partners. This article outlines the framework — not personal advice — and interpretation of “regularly paid” by the Czech tax authorities isn’t fully settled by published case law, which is exactly where specialist cross-border tax advice earns its fee.
Talk to us
Aisa International works with British nationals relocating across Europe, including to the Czech Republic, to structure UK pension withdrawals for tax efficiency in both jurisdictions.
